
Business Crypto Card Management: A 2026 Playbook
Business Crypto Card Management: A Practical Guide for 2026
Managing corporate spending with crypto used to mean juggling wallets, exchanges, and manual conversions. Business crypto cards change that. They turn stablecoins and other digital assets into spendable balances on standard Visa or Mastercard rails, so finance teams can pay for ads, software, travel, and cloud services without first moving funds through a traditional bank account.
But a card program is only as good as its management layer. Limits, approvals, merchant controls, reconciliation, and custody all determine whether crypto cards become a reliable treasury tool or a compliance headache. This guide explains how business crypto card management works, what to look for in a provider, and how to build a workflow that scales.
What Business Crypto Card Management Actually Means
Business Crypto Card Management: A 2026 Playbook - What Business Crypto Card Management Actually Means.
Business crypto card management covers the full lifecycle of corporate virtual and physical cards funded by digital assets. It includes:
- Issuance: Creating cards for employees, departments, or specific vendors.
- Funding: Depositing stablecoins such as USDT or USDC into a controlled account.
- Spending controls: Setting per-card limits, merchant categories, and expiration rules.
- Conversion and settlement: Converting crypto to fiat at authorization or settlement time.
- Reconciliation: Matching card transactions to accounting records and expense reports.
- Security and custody: Protecting funds, freezing cards, and managing fraud alerts.
- Compliance: KYC, AML, sanctions screening, and tax reporting.
A well-managed program treats a crypto-funded card like any other corporate payment instrument: visible, controlled, and auditable. The difference is the funding source and the conversion mechanics behind it.
How Business Crypto Card Issuance Works
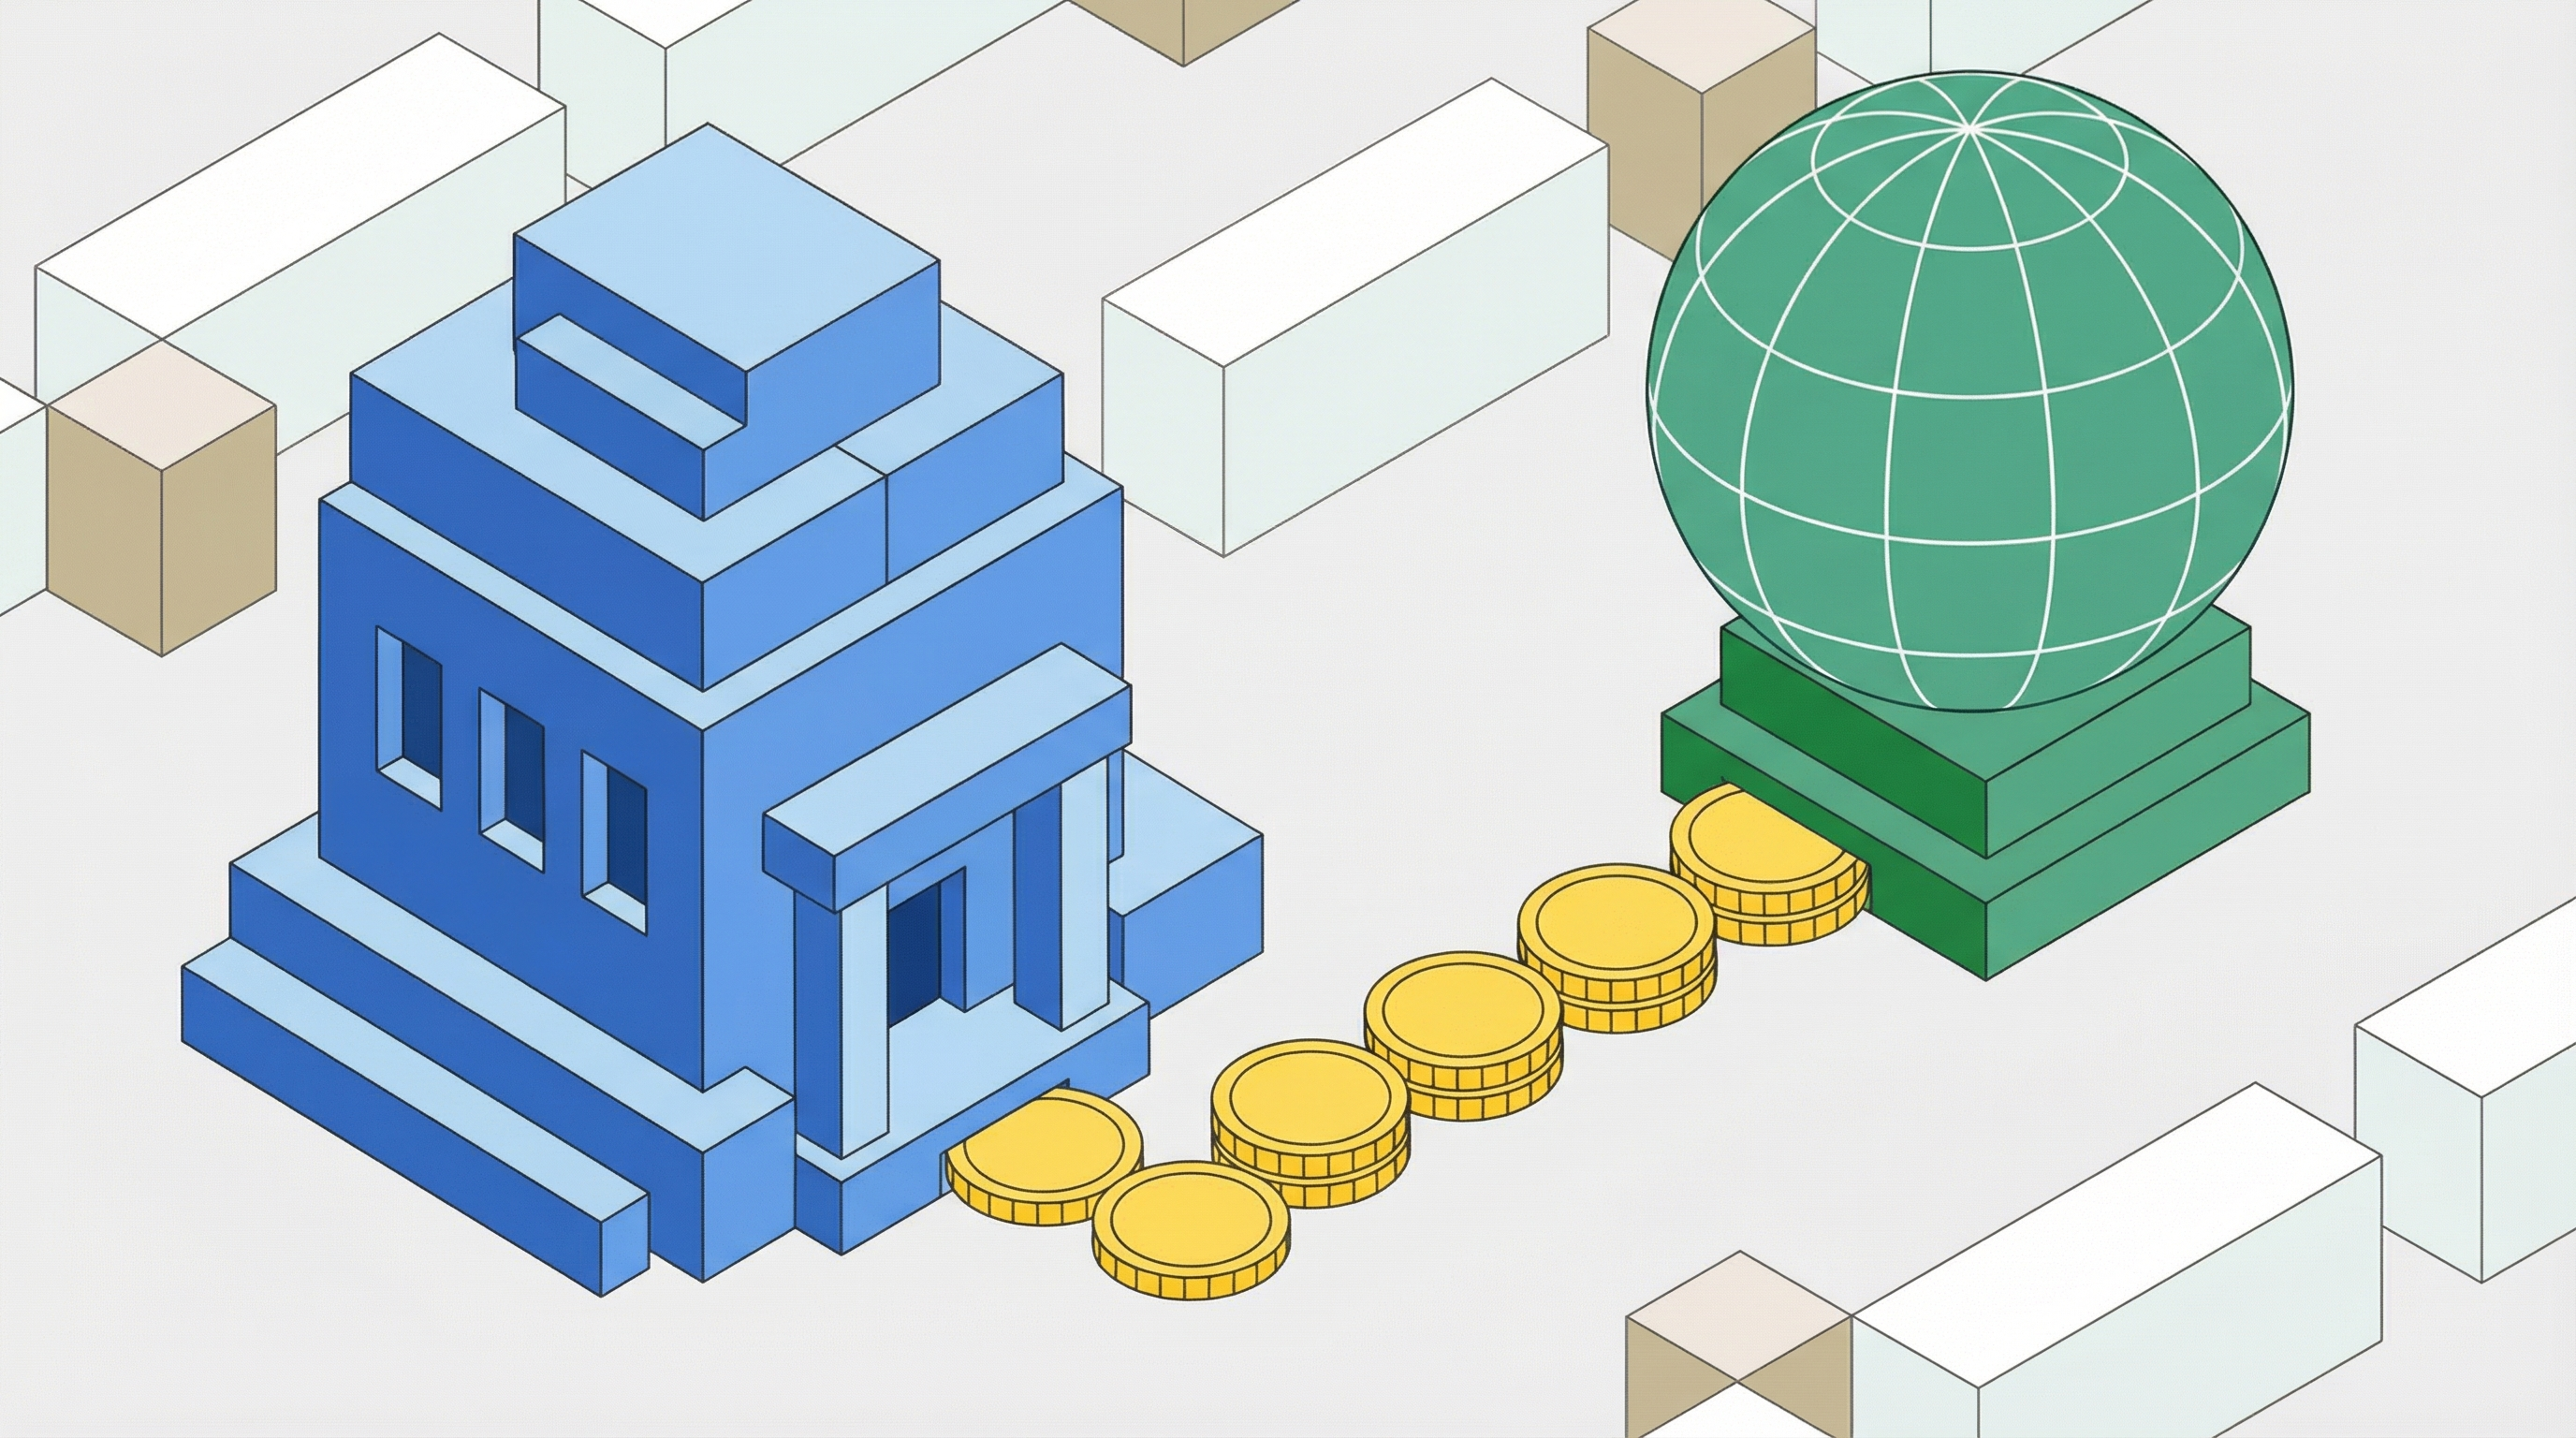
Business Crypto Card Management: A 2026 Playbook - How Business Crypto Card Issuance Works.
Only licensed entities can issue cards on major networks. A crypto platform therefore partners with an issuing bank or a modern issuing platform that provides the regulatory foundation, BIN sponsorship, and network access. The issuer handles KYC and AML checks, while the crypto platform builds the user-facing experience: sign-up, wallet integration, balances, card controls, fraud monitoring, and settlement.
When an employee pays with a crypto card, three things happen in sequence:
- Authorization: The merchant sends a request through the card network. The issuer checks with the crypto platform to confirm the card has enough value.
- Conversion: The platform sells the exact amount of crypto needed at real-time market rates and approves the transaction.
- Settlement: The merchant receives local currency, the card balance decreases by the equivalent amount, and the platform settles fiat with the issuer.
Because this runs on existing card networks, crypto cards work anywhere those networks are accepted, even at merchants that do not support crypto directly. That universality is the core appeal for businesses.
Why Businesses Use Crypto Cards
Business Crypto Card Management: A 2026 Playbook - Why Businesses Use Crypto Cards.
Crypto-native companies often hold significant working capital in stablecoins. Moving that capital into a traditional bank account for everyday spending adds friction, delays, and conversion costs. Business crypto cards remove those steps.
Common use cases include:
- Digital advertising: Funding Meta Ads, Google Ads, and TikTok Ads directly from stablecoin balances.
- AI and SaaS subscriptions: Paying for ChatGPT, Claude, Midjourney, AWS, Azure, Figma, and similar tools.
- Global travel and procurement: Issuing cards to remote teams or traveling employees without foreign transaction friction.
- Vendor payments: Paying contractors and suppliers that accept card payments.
For companies that already operate on stablecoin rails, crypto cards turn idle digital assets into working capital. For companies expanding globally, they reduce reliance on local banking relationships and simplify multi-currency spending.
Key Features to Look for in a Business Crypto Card Platform
Business Crypto Card Management: A 2026 Playbook - Key Features to Look for in a Business Crypto Card Platform.
Not all crypto card programs are built for corporate use. Consumer-focused cards often lack the controls and reporting that finance teams need. When evaluating a platform, focus on these capabilities:
1. Multi-Currency Virtual Cards at Scale
Corporate spending is rarely one card and one budget. You need the ability to issue dozens or hundreds of virtual cards, each tied to a specific team, vendor, or campaign. Multi-currency support matters if you pay for services billed in USD, EUR, GBP, or other currencies.
2. Stablecoin Funding
Volatile assets like Bitcoin or Ether create reconciliation problems. A card funded with USDT or USDC keeps balances predictable and reduces the risk that a market swing leaves a card underfunded. Leading business platforms focus on stablecoin funding for exactly this reason.
3. Real-Time Card Controls
You should be able to freeze a card instantly, set spending limits, restrict merchant categories, and expire cards without contacting support. Real-time controls are essential when a card is compromised or an employee leaves the company.
4. Automatic Multi-Currency Settlement
If your SaaS subscription bills in USD but your treasury holds USDC, the platform should handle conversion automatically at competitive rates. Manual conversions create delays and expose you to rate fluctuations.
5. High Limits for Ad Spend
Digital advertising often requires higher transaction volumes than consumer cards allow. Platforms designed for business use typically offer higher limits and dedicated virtual cards for ad platforms, which can also reduce account ban risks associated with shared payment methods.
6. Segregated Custody and Transparency
Where are client funds held? Are they lent, invested, or commingled with operating capital? The strongest platforms keep client funds in segregated accounts with third-party licensed custodians and state clearly that funds are never lent or invested. This matters for both security and auditability.
7. Compliance and Licensing
Payment, custody, and card-issuing activities should be performed through licensed partners. Look for regulatory approvals across the jurisdictions where you operate, such as Hong Kong, the UK, the US, or Canada. Security practices aligned with ISO/IEC 27001 are a strong signal.
Building a Management Workflow
Even the best card platform requires internal discipline. Here is a practical workflow for managing business crypto cards:
Step 1: Define Card Categories
Group cards by purpose. For example:
- Ad spend cards: One card per ad platform or campaign.
- SaaS cards: One card per subscription or department.
- Travel cards: Issued per trip or per employee.
- Procurement cards: For one-time vendor payments.
Dedicated virtual cards for ads are especially useful because they isolate spend and reduce the blast radius if a platform flags a payment method. You can learn more about this approach in our guide to dedicated virtual cards for ads.
Step 2: Fund a Single Treasury Account
Instead of funding each card individually, deposit stablecoins into one account and allocate budgets from there. This centralizes reconciliation and gives you a single view of total crypto spend. Platforms like Cardfornia are built around this model: fund once with USDT or USDC, then issue cards to teams at scale.
Step 3: Set Limits and Merchant Controls
Assign each card a monthly or per-transaction limit. Restrict merchant categories where possible. For example, an ad spend card should only work at Meta, Google, or TikTok. A travel card might be limited to airlines, hotels, and ground transportation.
Step 4: Automate Reconciliation
Export transaction data regularly and map it to your accounting system. Look for platforms that provide clean transaction exports, real-time webhooks, or API access. The less manual work required, the fewer errors you will find at month-end.
Step 5: Monitor and Review
Review card activity weekly. Look for unusual transactions, cards that are no longer needed, or limits that need adjustment. Freeze cards immediately when something looks wrong.
Risks to Manage
Business crypto cards sit at the intersection of blockchain and traditional card networks, which means they inherit risks from both worlds. The main areas to monitor are:
Regulatory Shifts
Crypto card programs operate under banking rules, card network rules, and crypto-specific regulations. Changes in local licensing, custody guidance, or stablecoin policy can affect onboarding, supported assets, or regional availability. Choose a provider with a track record of regulatory compliance and clear communication about changes.
Market Volatility and Liquidity
Every transaction requires crypto to be converted at live market rates. Stablecoins minimize this risk, but liquidity outages at exchanges can still cause temporary failures. Platforms that lock rates at authorization and maintain reliable liquidity partners reduce this exposure.
Tax Treatment
In many countries, spending crypto counts as disposing of an asset, which can create a taxable event. Each purchase may generate a gain or loss that needs to be tracked. Issuers typically provide transaction summaries, but businesses should maintain their own records and consult tax professionals. Stablecoin-funded cards simplify this because stablecoins are designed to maintain a 1:1 value with fiat, reducing the likelihood of material gains or losses.
Security and Custody
Traditional card fraud risks apply, as do risks to the crypto wallets backing the cards. Look for platforms that integrate KYC and AML controls, fraud monitoring across fiat and blockchain patterns, instant card freezes, real-time alerts, and strong multifactor authentication. Segregated custody with third-party licensed custodians is a meaningful safeguard.
Comparing Business Crypto Card Providers
When shortlisting providers, use this framework:
| Criteria | What to Ask |
|---|---|
| Use case fit | Does the platform support your primary spend categories: ads, SaaS, AI tools, travel? |
| Funding model | Can you fund with USDT, USDC, or other stablecoins? Is funding centralized or per-card? |
| Card controls | Are limits, freezes, and merchant restrictions available in real time? |
| Settlement | How are multi-currency transactions settled? What are the FX costs? |
| Custody | Are client funds segregated? Held with licensed custodians? Never lent or invested? |
| Compliance | Which jurisdictions are covered? What KYC and AML processes are in place? |
| Limits | Are limits high enough for ad spend and enterprise procurement? |
| Reporting | What transaction data is exportable? Is there API or webhook access? |
For a deeper look at how one platform performs against these criteria, see our Cardfornia review.
How Cardfornia Fits Into Business Crypto Card Management
Cardfornia is a Singapore-based fintech platform that provides crypto virtual cards designed specifically for corporate businesses and startups. The platform addresses the operational needs of crypto-native companies and globally scaling businesses by connecting stablecoin treasuries to everyday business spending.
The core workflow is straightforward: fund a single account with USDT or USDC, issue multi-currency virtual cards to teams at scale, and maintain real-time control over operating expenses. This centralized funding model simplifies reconciliation and gives finance teams a single source of truth for crypto spend.
Cardfornia emphasizes several features that matter for business card management:
- High-limit cards for ad spend to reduce account ban risks on Meta, Google, and TikTok.
- Automatic multi-currency settlement for SaaS and cloud subscriptions.
- Real-time currency exchange for cross-border transactions.
- Segregated custody: client funds are held 100% in segregated accounts with third-party licensed custodians and are never lent or invested.
- Security practices guided by ISO/IEC 27001 standards, with payment, custody, and card-issuing activities performed through licensed partners holding regulatory approvals across Hong Kong, the UK, the US, and Canada.
For teams that already hold stablecoins and want to reduce the friction of moving funds through traditional banking rails, this model can replace a patchwork of individual wallets and consumer cards with a single managed program. If you are still working through the broader question of how to streamline crypto payments across your business, our guide to simplifying business crypto payments covers the infrastructure decisions in more detail.
Common Mistakes to Avoid
1. Using Consumer Cards for Business Spend
Consumer crypto cards often lack the limits, controls, and reporting that businesses need. They may also have lower transaction caps that make ad spend or enterprise procurement impractical.
2. Funding Cards with Volatile Assets
Bitcoin and Ether are fine for investment portfolios, but they create reconciliation complexity when used for everyday spending. Stablecoins keep balances predictable and reduce tax reporting burden.
3. Ignoring Custody Structure
If a platform lends or invests client funds, your working capital is exposed to risk you did not sign up for. Always verify where funds are held and whether they are segregated.
4. Skipping Internal Controls
Even with a good platform, you need internal policies: who can issue cards, what limits apply, and how transactions are reviewed. Technology is not a substitute for process.
5. Overlooking Foreign Transaction Dynamics
If your business pays for services in multiple currencies, foreign card declines and dynamic currency conversion fees can add up. Understanding why foreign card declines happen helps you choose a platform with reliable multi-currency settlement.
Related reading
- USD/CNY Exchange Rate: How the Dollar-Yuan Pair Works - Understand the USD/CNY exchange rate, what drives the dollar-yuan pair, how to read live quotes, and what it means for businesses and cross-border payments.
Sources and further reading
- Crypto Cards: A Guide for Businesses | Stripe - Learn what crypto cards are, how they work, their risks and benefits, and how your business can choose the right crypto card partner.
- Making everyday purchases with crypto cards - Mastercard - Enables consumers to transfer fiat balances in their crypto wallets to their card or bank account. Explore. Small business. Mastercard Crypto Credential. Enable ...
- Wirex | Crypto Wallet, Cards & Payments for All - Wirex is a crypto wallet and payment platform with cards, exchange, yield products, and global transfers — simple, secure, and user-centric.
Frequently Asked Questions
What is a business crypto card?
A business crypto card is a payment card issued to a company that is funded by cryptocurrency, typically stablecoins like USDT or USDC. At checkout, the card converts the required amount of crypto into fiat at the current rate, and the merchant receives a standard card payment in local currency.
How does business crypto card management differ from consumer crypto cards?
Business programs include features that consumer cards typically lack: bulk card issuance, per-card spending limits, merchant category restrictions, centralized funding, multi-currency settlement, higher transaction limits, and detailed reporting for reconciliation.
Are crypto card transactions taxable?
In many jurisdictions, spending crypto can be treated as disposing of an asset, which may create a taxable event. Stablecoin-funded cards generally simplify this because stablecoins aim to maintain a 1:1 value with fiat. Businesses should maintain transaction records and consult tax professionals.
Can I use a business crypto card for digital advertising?
Yes. Many crypto-native companies use dedicated virtual cards for Meta Ads, Google Ads, and TikTok Ads. High-limit cards and isolated payment methods can reduce account ban risks and simplify budget tracking. See our guide to digital marketing crypto cards for details.
What should I look for in a business crypto card provider?
Prioritize stablecoin funding, real-time card controls, multi-currency settlement, high limits, segregated custody with licensed custodians, regulatory compliance in your operating jurisdictions, and strong reporting or API access.
How do I keep business crypto card funds safe?
Choose a platform that keeps client funds in segregated accounts with third-party licensed custodians, never lends or invests those funds, and follows security practices aligned with ISO/IEC 27001. Internally, enforce card limits, freeze cards immediately when needed, and review activity regularly.
Conclusion
Business crypto card management is about more than issuing a card. It is about building a controlled, auditable spending pipeline that connects stablecoin treasuries to the vendors, platforms, and services your business relies on every day.
The best programs combine centralized stablecoin funding, real-time card controls, automatic multi-currency settlement, and segregated custody. They give finance teams the same visibility and control they expect from traditional corporate cards, without forcing crypto-native companies to route every payment through a bank account first.
As you evaluate options, start with your use case: which spend categories matter most, which currencies you need, and what level of control your finance team requires. Then choose a provider that matches those needs with transparent custody, strong compliance, and a management layer built for scale.